Shopfitting Depreciation Schedule After a Business Purchase: What Australian Buyers Need to Know
When you buy a business that includes a fitted-out retail or commercial space, understanding how to handle the cost of those fit-out assets on your tax return can save you a significant amount of money over time. This article breaks down everything Australian business buyers need to know about shopfitting depreciation schedules, from the basics through to practical steps for getting one in place.
What Is a Shopfitting Depreciation Schedule?
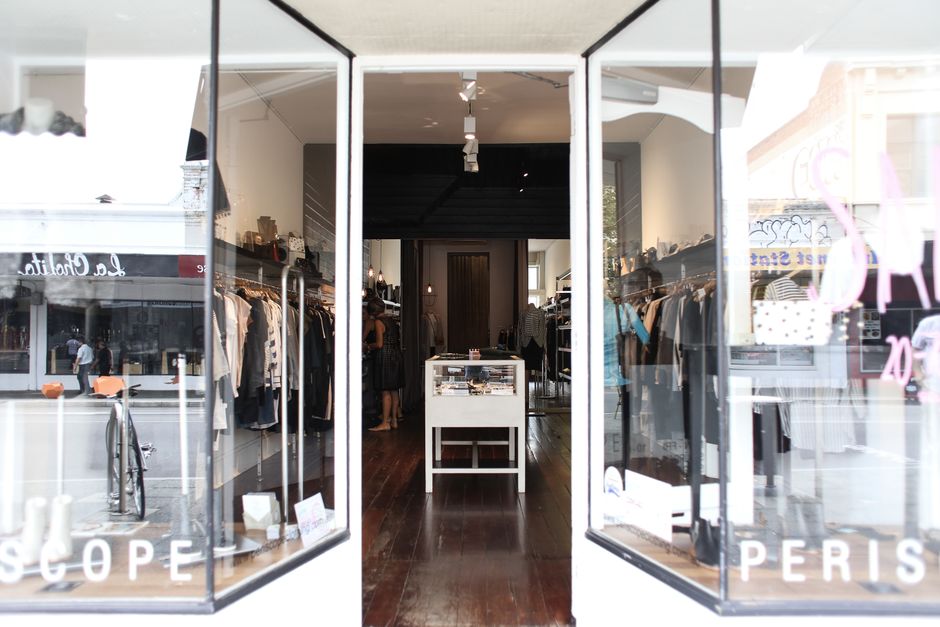
A shopfitting depreciation schedule is a formal document that identifies, values and assigns depreciation rates to the physical fit-out assets inside a commercial premises. Think display counters, shelving, lighting rigs, flooring, signage, point-of-sale fixtures and built-in cabinetry. These are not permanent parts of the building structure. They are depreciable plant and equipment, and the Australian Taxation Office allows business owners to claim a deduction on them year after year as they wear out.
When you purchase a business, you are often acquiring these fit-out assets as part of the deal. The depreciation schedule tells both you and the ATO exactly what those assets are worth at the time of purchase, and how quickly their value declines under the effective life rules set out by the ATO.
A qualified quantity surveyor or depreciation specialist typically prepares the schedule. It lists every eligible asset, its individual value, its effective life in years, and the annual deduction you can claim using either the prime cost method or the diminishing value method.
For buyers of retail shops, cafes, salons, gyms or any fitted commercial space, this document is not just a nice-to-have. It is a core part of understanding the true tax position of the business you are stepping into. Without one, you are likely leaving legitimate deductions unclaimed and paying more tax than you need to from day one of ownership.
How Shopfitting Assets Are Classified for Tax Purposes
When you buy a business with an established fit-out, the Australian Taxation Office does not treat shopfitting as a single lump-sum asset. Instead, the ATO requires you to break the fit-out down into individual asset categories, each with its own effective life and depreciation rate. Getting this classification right from day one has a direct impact on how much you can claim each year.
Broadly speaking, shopfitting assets fall into two categories under the tax rules:
- Division 43 capital works: This covers structural elements permanently attached to the building, such as partition walls, fixed shelving built into the structure, floor coverings that are part of the building fabric, and fitted ceilings. These are written off at a flat rate of 2.5 percent per year over 40 years.
- Division 40 plant and equipment: This covers removable or mechanical assets, including display cases, refrigeration units, point-of-sale counters, lighting rigs, signage, and air conditioning units. These assets each carry an ATO-assigned effective life and are depreciated using either the prime cost or diminishing value method.
The distinction matters enormously when you are buying a retail or hospitality business. A café fit-out, for example, might include commercial ovens (plant and equipment), a tiled splashback built into the wall (capital works), and freestanding display furniture (plant and equipment). Each item sits in a different category with a different rate.
Buyers who simply lump everything together as a single fit-out asset often miss out on accelerated deductions available on shorter-life plant and equipment items. A qualified quantity surveyor or tax depreciation specialist can prepare a formal depreciation schedule that correctly splits the fit-out, giving you the clearest possible picture of your annual deductions before you even settle on the deal.
Depreciation Methods and Effective Lives for Shopfitting
When you purchase a business with existing shopfitting, the Australian Taxation Office gives you two main methods for claiming depreciation: the prime cost method and the diminishing value method. Choosing the right one can make a meaningful difference to your cash flow in the early years of ownership.
- Prime cost method: Deductions are spread evenly across the asset's effective life. This suits buyers who want predictable, consistent deductions each year.
- Diminishing value method: Front-loads larger deductions in the earlier years, which can offset the higher costs that typically come with settling into a new business.
The ATO publishes effective life guidelines for shopfitting assets, and these vary considerably depending on the asset type. A rough breakdown looks like this:
| Asset Type | Typical Effective Life |
|---|---|
| Fit-out partitions and walls | 10–20 years |
| Shelving and display fixtures | 6–10 years |
| Lighting installations | 5–10 years |
| Carpets and floor coverings | 8–10 years |
| Air conditioning units | 10–15 years |
One important consideration for business buyers is that you can elect to use your own self-assessed effective life if you have evidence the assets will wear out faster than the ATO's published figures. Retail environments with high foot traffic often justify a shorter effective life for floor coverings and fixtures.
Navigating these choices correctly at the point of purchase is where many buyers leave money on the table. Our Guides section covers related tax and valuation topics in plain English, and if you want tailored guidance on your specific deal structure, you are welcome to get in touch with a question about your transaction.
Claiming Depreciation After a Business Purchase
When you buy an existing business that includes a fitted-out premises, the shopfitting depreciation schedule becomes one of your most valuable tax tools from day one. Many buyers overlook this, but the Australian Taxation Office allows you to claim depreciation on the plant and equipment assets you acquire as part of the purchase, not just the ones you install yourself.
To get your claims right from the start, there are a few key steps to work through:
- Apportion the purchase price correctly. The contract price for a business usually covers goodwill, stock, equipment and fitout assets together. A quantity surveyor or registered tax agent can help you allocate a defensible value to the depreciable fitout items separately.
- Establish the effective life of each asset. The ATO publishes effective life schedules for common shopfitting components. Buyers inherit the remaining effective life of each item, which directly affects how much you can claim each year.
- Choose the right depreciation method. The prime cost method spreads deductions evenly across an asset's life, while the diminishing value method front-loads larger deductions in the earlier years. For a new owner wanting strong early cash flow, the diminishing value approach is often worth considering.
- Check eligibility for instant asset write-off. Depending on your business turnover and the thresholds in place for the current financial year, some fitout assets may qualify for an immediate deduction rather than being depreciated over time.
Importantly, second-hand depreciating assets acquired in a business purchase are treated differently under current tax rules than brand-new assets. Getting specialist advice at the time of settlement, rather than at tax time, means you capture every legitimate deduction available to you and set up your depreciation schedule on solid footing from the moment you take ownership.
Working With a Quantity Surveyor to Prepare Your Schedule
When you buy a business with significant shopfitting assets, engaging a qualified quantity surveyor is one of the smartest moves you can make before lodging your first tax return. The ATO expects depreciation schedules to be prepared or reviewed by a competent professional, and a quantity surveyor has the specific training to estimate the original construction cost of fit-out items even when the seller cannot provide original invoices.
Here is what a good quantity surveyor will typically do for a shopfitting depreciation schedule:
- Inspect the premises in person to catalogue every depreciable asset, from structural improvements to loose plant and equipment.
- Estimate the effective life of each item using ATO guidelines and their own professional judgment.
- Assign an opening value at the date of settlement, which forms the starting point for your deductions.
- Separate Division 43 capital works from Division 40 plant and equipment, so each category is claimed at the correct rate.
- Produce a written report you and your accountant can rely on if the ATO ever asks questions.
Fees for a commercial quantity surveyor report typically range from a few hundred dollars for a small retail tenancy to over a thousand dollars for a larger or more complex fit-out. That cost is itself tax deductible, and the deductions unlocked almost always far outweigh the fee within the first year.
Ask your business broker or solicitor for a referral, or look for a surveyor who is a member of the Australian Institute of Quantity Surveyors. Make sure they have specific experience with commercial fit-outs rather than purely residential property work.
Putting together a solid shopfitting depreciation schedule takes some upfront effort, but the long-term tax savings make it a core part of any smart business purchase strategy in Australia. From understanding effective life categories through to working with the right professionals, buyers who get this right from day one consistently keep more of their hard-earned profit.